Guide to Car Repair Loans
Key takeaways
- Major repairs (an engine, transmission or accident damage) can run into the thousands and rarely arrive with warning.
- There's more than one way to pay: savings, mechanical breakdown insurance, a credit card or a personal loan each suit different situations.
- A personal loan spreads a large repair bill over fixed repayments, with funds paid to your account so you choose the workshop.
- Every lender must assess affordability under the Credit Contracts and Consumer Finance Act (CCCFA) before approving a loan, including one for repairs.
- If a repair bill has tipped you into financial difficulty, free help is available from MoneyTalks.
Guide to car repair loans
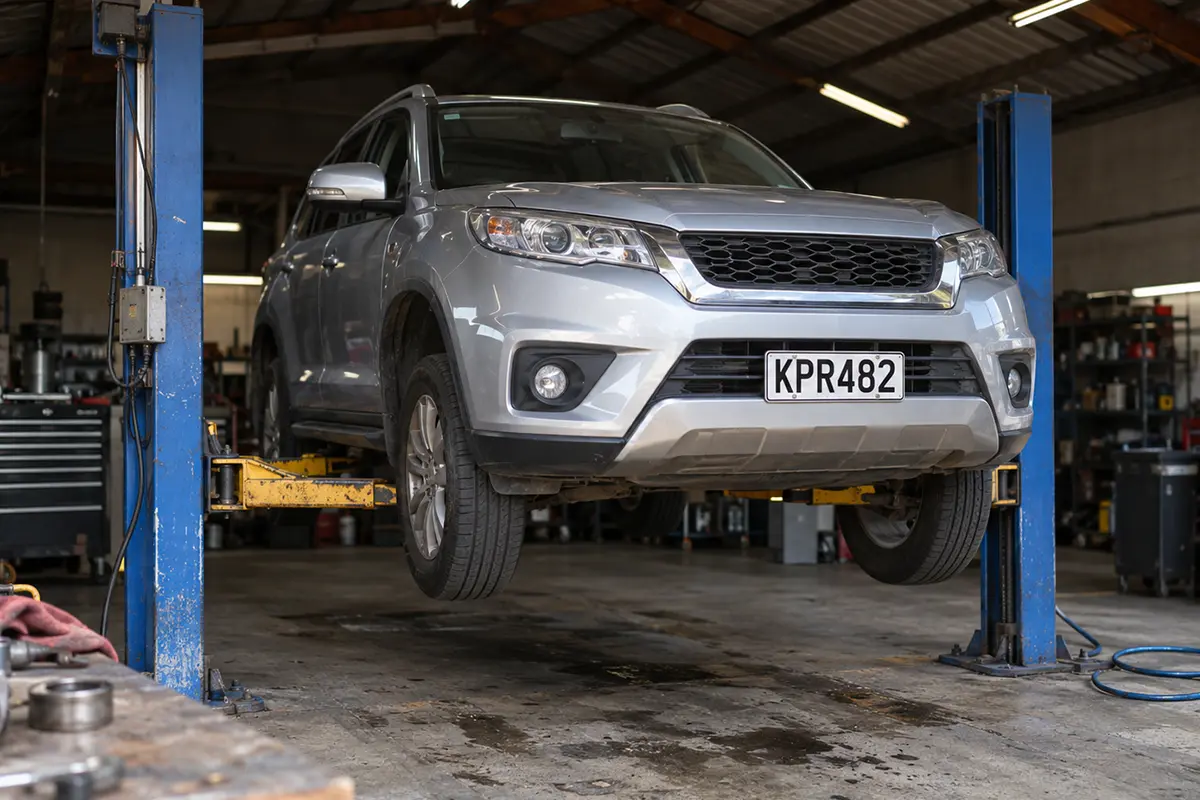
Most car trouble starts small - a noise, a light on the dash, a mechanic saying "you'll want to get that looked at." Then the quote comes back and it's not a small job after all. A failed transmission, a damaged engine or panel damage that insurance doesn't fully cover can cost more than many households hold in current savings.
For most New Zealanders the car isn't optional. It's how you get to work, get the kids to school and keep life running. That's what makes a major repair bill different from most unexpected costs: waiting usually isn't a realistic option, and the pressure to decide quickly is exactly when it's worth knowing what your payment options actually are.
What counts as a major repair
There's no official definition, but in practice a major repair is one you can't absorb in a normal pay cycle. Common examples include:
- Engine work - head gaskets, timing chain or cambelt failure, or a full rebuild or replacement.
- Transmission and gearbox - often one of the most expensive single repairs on a modern vehicle.
- Accident damage - panel and structural work where you're not covered, or where an excess and uninsured items still leave a large bill.
- Electrical and electronic faults - increasingly costly on newer vehicles with complex systems.
- A long WOF failure list - individually small items that add up to one large bill when they all arrive at once.
- Smaller jobs - tyres, brakes, a service, are usually better handled from regular income or savings. Borrowing suits the big, one-off bills, not routine running costs.
Why repairs cost more than they used to
Modern vehicles are safer and more efficient, but that technology has a price when something goes wrong.
Driver-assist systems mean even a windscreen replacement can now involve recalibrating cameras and sensors. Bumpers house parking sensors and radar. Diagnosing an electronic fault takes specialist equipment and workshop time that an older car simply didn't need.
The result is that jobs which used to be modest can now land in major-repair territory - which is why more New Zealanders are having to think about how they'd pay for one.
Your options for paying for a major repair
Savings or an emergency fund
If you have savings set aside, this is usually the cheapest option — there's no interest and no fees. Sorted's guide to emergency savings is a good starting point for rebuilding the buffer afterwards.
Mechanical breakdown insurance
If you bought mechanical breakdown insurance (MBI) with your vehicle, check the policy before paying anything yourself. MBI can cover some major mechanical failures, but policies can vary in what they exclude - wear and tear, servicing history conditions and claim limits all matter. Read the policy wording or call the insurer first.
Credit cards
A credit card can work for a bill you can clear quickly. The risk is carrying a large balance at a high interest rate with no fixed end date — a four-figure repair that sits on a card for a year can end up costing considerably more than the repair itself.
A personal loan
A personal loan converts one large bill into fixed weekly or fortnightly repayments over a set term, so you know the total cost and the end date from day one. For major repairs this structure is the main advantage over revolving credit: the debt is designed to be gone by a known date.
How a personal loan for car repairs works
A repair loan is simply a personal loan used for a repair - there's no special product category. A few practical points:
Loan amounts
Most lenders set minimum loan amounts. Loans arranged through Nomu start from $5,000, which suits major repairs - or a repair combined with other costs that have arrived at the same time.
Debt consolidation
Where a repair bill arrives alongside several existing repayments (cards, buy now pay later, another loan) it's sometimes worth exploring whether consolidating them into one loan with the repair makes the overall position more manageable. It depends entirely on the numbers, so compare total cost before and after.
Funds paid to you
The money goes to your bank account, not the workshop - so you choose who does the work and you pay them directly.
Secured or unsecured loans
Lenders may offer a lower rate if the loan is secured against an asset, such as the vehicle itself. Unsecured loans don't put an asset at risk but generally carry higher rates. Which suits you depends on your situation.
Loan terms
Repayment terms commonly run from one to seven years. A shorter term costs less in total interest; a longer term lowers the regular repayment. It's worth comparing both numbers, not just the weekly figure.
What lenders look at
A repair loan is assessed the same way as any other personal loan. Under the Credit Contracts and Consumer Finance Act (CCCFA), lenders must be satisfied the repayments are affordable without causing you substantial hardship. In practice that means they'll look at:
- Income and expenses - usually through recent bank statements, which show how money actually moves through your accounts.
- Your credit file - repayment history, existing debts, and any defaults or recent applications.
- Existing commitments - other loans, cards and buy now pay later balances all count.
- Credit history - If your credit history has a few marks on it, that doesn't automatically rule out approval - some lenders weigh recent behaviour more heavily than old problems.
Being upfront about your situation from the start gives an application its strongest footing. For more detail, see our guide to what lenders look at when assessing loan applications.
If you're already stretched
Borrowing only helps when the repayments genuinely fit your budget. If the repair bill has arrived on top of existing money pressure, taking on more debt may not be the right move - and there is free, confidential help available.
MoneyTalks (0800 345 123) offers free financial mentoring and can help you work through options.
If you already have a loan and are struggling with repayments, you can apply to your lender for a hardship variation - contact them early rather than missing payments.
Sorted also has free tools for budgeting and planning to assist in getting back on track.
Common Questions
Ready to get started?
Personal loans that work for you

The information in this article is general in nature and is provided for educational and informational purposes only. It does not constitute financial advice and should not be relied on as a substitute for personalised advice tailored to your individual circumstances.
Nomu Finance Limited (FSP1011169) holds a Class 1 Financial Advice Provider (FAP) licence issued by the Financial Markets Authority. Personalised financial advice is only provided following a full assessment of your individual needs and circumstances by a Nomu Finance adviser.
Any examples, figures, or scenarios in this article are illustrative only and do not represent a credit offer or guarantee of approval. Lending criteria apply.
If you are considering taking out a loan or making any financial decision, we encourage you to speak with an independent licensed financial adviser or get in touch with one of the team at Nomu, to get advice tailored to your circumstances.