Electric Vehicle Loans in NZ 2026
Key takeaways
- EVs can be financed as secured personal loans, the same structure as a standard car loan
- New Zealand's used EV market has grown significantly, with imported Japanese and European models widely available across a range of price points
- Battery health is the most important additional check for any used EV purchase, replacement costs can be significant and may not be covered by standard insurance
- EVs generally cost less per kilometre to run than petrol equivalents, even with road user charges now applying, but the purchase price is typically higher, making finance a common pathway
- A broker working across a panel of lenders can identify which options suit both new and used EV purchases
Electric Vehicle Loans in NZ
Most EV finance in NZ is for new vehicles, and it works like any new car purchase: the registered value is reliable, manufacturer warranties apply, and lender criteria are straightforward.
The second-hand market is younger, but growing, and a used EV needs a few extra checks before you commit. Battery health is the big one, covered below. For Japanese imports, NZ compliance is handled at the time of import; registration and WOF apply as with any other vehicle.
How EV finance works in NZ
Financing an electric vehicle in NZ follows the same process as financing any other car. Most EVs (new or used) are financed as secured personal loans, with the vehicle used as collateral. This gives the lender security if the loan is not repaid and generally means a lower rate than unsecured lending.
The lender assesses the vehicle's registered value, age, and condition alongside the borrower's income, expenses, and credit history. For newer EVs with reliable registered values, this is usually straightforward. For imported used models, the registered value and any required compliance work are relevant to the assessment.
New versus used EV finance
New EVs from authorised dealers are financed in the same way as any new vehicle. The registered value is reliable, dealer guarantees apply, and lender criteria are typically straightforward to meet.
Used and imported EVs require a few additional checks. Most imported EVs arrive from Japan, where odometer readings are in kilometres and compliance with NZ standards is handled at the time of import. A compliance check confirms the vehicle meets NZ requirements. Registration and WOF apply as with any other vehicle.
What to check before financing a used EV
Battery health and range
The battery is the most important component of any electric vehicle and the one most affected by age and use patterns. Battery degradation reduces range. An EV with a stated range of 250km may deliver significantly less after several years of real-world use. Most modern EVs display a battery health or state of health (SoH) percentage. For any used EV purchase, request the battery health report before committing. A healthy battery typically shows SoH above 80%.
Battery replacement costs are significant, ranging from several thousand dollars to over $20,000 for some models. Standard vehicle insurance does not cover battery degradation, and Mechanical Breakdown Insurance (MBI) policies vary in their coverage of EV-specific components. Check policy terms carefully.
Charging infrastructure
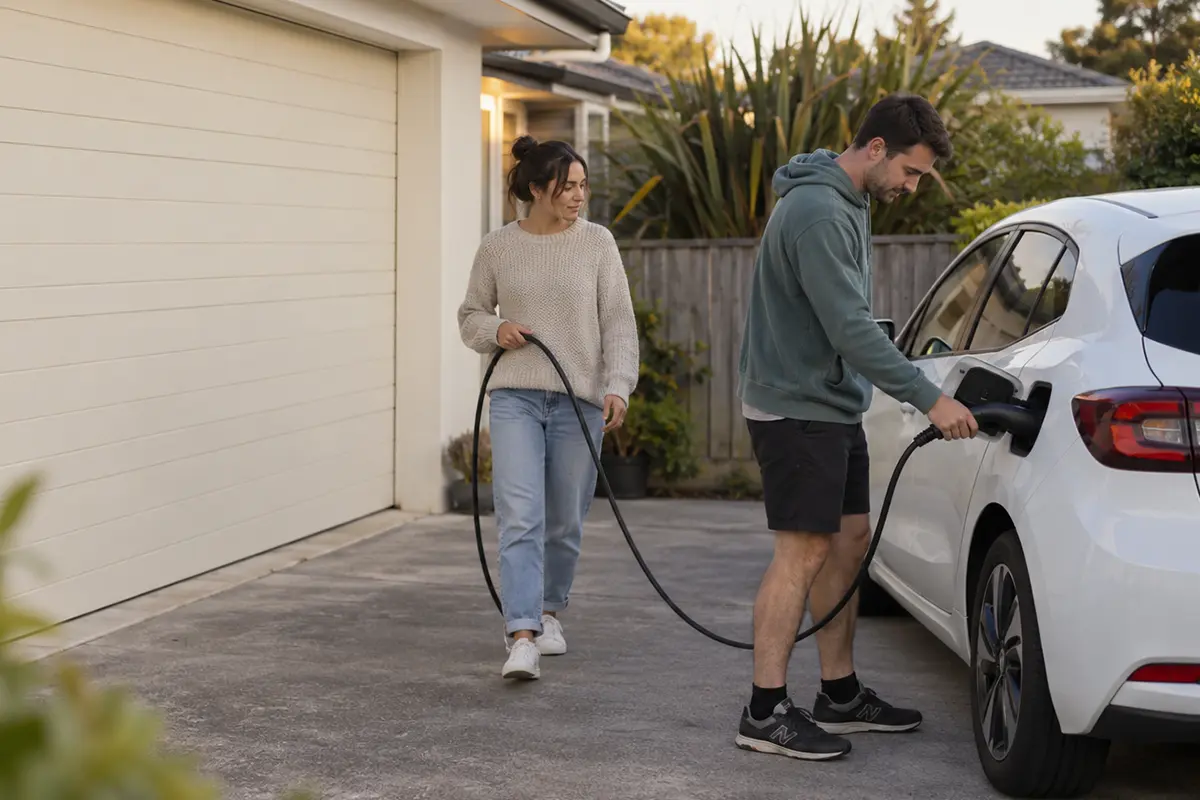
Access to home charging is a significant factor in EV running costs. Home charging on overnight off-peak rates is the most cost-effective way to charge, but requires a compatible home charger setup. Public fast-charging networks in NZ have expanded but remain unevenly distributed outside main centres. Check charging availability for your regular routes before purchasing - the EVRoam charging map at journeys.nzta.govt.nz shows public chargers across NZ.
Import compliance and vehicle history
For imported used EVs, confirm that NZ compliance has been completed and that the vehicle is registered and warrant of fitness-compliant. NZTA's vehicle information service shows registration, WOF status, and odometer history. A PPSR check confirms no existing finance is registered against the vehicle.
Running costs versus loan cost
EVs generally cost less per kilometre to run than petrol vehicles - electricity is cheaper than petrol per unit of energy, and EVs require less routine maintenance (no oil changes, fewer brake replacements due to regenerative braking).
One change worth factoring in: since April 2024, EVs pay road user charges, which they were previously exempt from. RUC narrows the running-cost gap with petrol vehicles, though for most drivers EVs still work out cheaper per kilometre overall once electricity, maintenance and RUC are counted together. EECA publishes vehicle running-cost comparisons via their website.
The trade-off is that the purchase price of an EV is typically higher than a comparable petrol vehicle, which is why finance is a common pathway. When comparing total cost of ownership (purchase price plus running costs over the loan term ) EVs often compare favourably with petrol equivalents for higher-mileage drivers.
What it typically costs to run an EV
Indicative 2026 figures for a light EV doing around 12,000 km a year. Actual costs vary by vehicle, region and driver.
Figures are general estimates only, not quotes. Check current RUC rates at nzta.govt.nz.
Want figures for a specific model? EVDB's running cost calculator at evdb.nz compares any EV against a petrol equivalent using NZ electricity and fuel prices.
Financing an EV through Nomu Finance
The process is the same one application used for any vehicle loan.
- Apply online. A few minutes, one form. If you've found the car, tell us about it — or apply first and set your budget before you start looking.
- We find your options. Your application is assessed and matched to the lenders whose criteria fit your situation and the vehicle, new or used. You get a straight answer and, where it works, options with real numbers.
- Choose and proceed. Pick the loan that fits, sign, and funds are typically available within 24 hours of approval.
You don't need to have chosen the car before applying. Knowing your budget before you walk into a dealership (or bid on an import) puts the decision back on your side of the table. Use the loan calculator to get a feel for repayments first.
The bottom line
An EV loan is a car loan. What's different is the vehicle: battery health, real-world range, charging access, and a running-cost picture that now includes road user charges. Get those checks right, sort the finance before you shop, and the rest is the same one
Common Questions
Ready to get started?
Personal loans that work for you
The information in this article is general in nature and is provided for educational and informational purposes only. It does not constitute financial advice and should not be relied on as a substitute for personalised advice tailored to your individual circumstances.
Nomu Finance Limited (FSP1011169) holds a Class 1 Financial Advice Provider (FAP) licence issued by the Financial Markets Authority. Personalised financial advice is only provided following a full assessment of your individual needs and circumstances by a Nomu Finance adviser.
Any examples, figures, or scenarios in this article are illustrative only and do not represent a credit offer or guarantee of approval. Lending criteria apply.
If you are considering taking out a loan or making any financial decision, we encourage you to speak with an independent licensed financial adviser or get in touch with one of the team at Nomu, to get advice tailored to your circumstances.